Safex · 20 MIN READ
Why Safex Uses Proof of Work: Consensus, Commerce, and the Right to Participate
How blockchain consensus works, why Safex uses CPU mining, and how SFX and SFT support open participation, marketplace accounts and useful commerce.
 Daniel Dabek · October 17, 2026
Daniel Dabek
I came to Bitcoin through the practical problem of paying people. I wanted to import products, and I found software developers who accepted bitcoin. Being able to pay across borders, at night, or on a weekend made it possible to work with people I otherwise would have struggled to reach. I described that experience in a 2018 interview. It remains a useful place to begin any discussion of cryptocurrency.
Someone has a skill. Someone else needs it. They should be able to find one another, agree on terms, and exchange value. The money and the marketplace should help that relationship develop.
That is the reason for Safex. It is also the reason its consensus model matters.
A person may spend years building a business online. Their savings, customers, reputation, and ability to earn become part of their life. If we want that progress to endure, we have to ask who controls the system recording it, who can participate in operating that system, and what happens when its participants disagree.
Proof of work is part of my answer. So are privacy, a deliberate approach to monetary distribution, and the distinct functions of Safex Cash and Safex Token. SFT is used to establish marketplace accounts by committing tokens. It also has a separate role in sharing marketplace fees through staking. Understanding those functions is essential to understanding why Safex uses mining to secure the network.
What consensus actually decides
A blockchain is a shared record maintained by computers that can disagree, disconnect, or behave dishonestly.
Suppose a buyer tries to spend the same money twice. One seller sees the first payment. Another sees the second. Both transactions may carry a legitimate signature from the buyer. A signature proves authorization; it does not establish which competing spend the network should accept.
Consensus supplies the rules for reaching a common history.
Several parts have to work together. Transaction rules determine what is valid. A mechanism determines who can propose blocks or vote on them. A fork choice rule resolves competing histories. Confirmation or finality rules tell participants how strongly the accepted history is protected.
There is also the problem of fake participants. Creating ten thousand network identities must not give one person ten thousand independent votes. This is usually called the Sybil problem. Proof of work and proof of stake address it by attaching influence to a scarce resource. They are components of a complete consensus system, as the Ethereum documentation itself explains.
For a marketplace, these decisions have direct consequences. They affect whether a merchant can rely on payment, whether newcomers can help operate the network, and how much power can accumulate in a small group.
The main approaches to consensus
Proof of work: committing computing resources
In proof of work, miners repeatedly perform computations to find a result that satisfies the network's difficulty requirement. Finding a qualifying result takes repeated attempts. Other nodes can check the result and the proposed block.
The proof makes block production costly without asking a registrar to decide who is allowed to compete. Creating more identities does not create more computing capacity.
Bitcoin's design combines this competition with a chain selection rule based on accumulated work. The important quantity is the work represented by a valid chain, rather than the number of computers announcing their agreement. A competing history has to accumulate the work necessary to overtake the accepted history. Bitcoin's white paper explains this relationship between work, competing branches, and double spending.
Miners propose history, while validating nodes enforce the rules. A block that invents an unauthorized reward or spends coins without the required authorization remains invalid even if its creator controls substantial computing power. The Bitcoin developer guide makes this distinction clear.
Settlement is probabilistic. Additional confirmations increase the work an attacker would need to overcome, under the assumptions of the security model. A merchant accepting a large payment must consider network conditions and confirmation depth.
The cost is real: equipment, electricity, maintenance, and the possibility of doing work that earns no reward. That continuing expense is also a barrier an attacker must confront.
Proof of stake: committing the network's own asset
Proof of stake assigns participation weight through assets committed within the system. Validators propose and attest to blocks according to the protocol. The details differ substantially between networks.
Ethereum, for example, uses stake weighted votes and checkpoint finality. Votes representing at least two thirds of the active stake are needed for the relevant finality decisions. Certain violations can result in slashing, meaning the validator loses part of its stake. Its proof of stake documentation describes these mechanisms.
This approach avoids the continuous competitive hashing of proof of work. It can provide explicit finality and economic penalties for provable misconduct. Those are meaningful properties.
My concern for Safex is the relationship between existing ownership and continuing influence over the network. A person entering the consensus process has to obtain the asset that the system already recognizes as stake. Participation weight then depends on that commitment.
It is too simplistic to say staking automatically makes every wealthy participant's percentage grow. If everyone earns and reinvests at the same rate, their percentages of the total stake can remain unchanged. The more useful questions concern initial distribution, access to staking, custody, delegation, and whether a few operators come to exercise much of the voting power.
There is also a distinction when joining a network after a long absence. Ethereum uses a recent trusted checkpoint to protect a returning or new node against misleading histories signed by validators whose stake has already been withdrawn. Its documentation calls this weak subjectivity.
That is a specific security assumption, with procedures for managing it. Understanding it is more useful than declaring every proof of stake system either perfect or broken.
Delegated proof of stake: electing block producers
Delegated proof of stake introduces a representative layer. Token holders vote for a set of producers who perform block production. The Antelope protocol documentation describes this separation between selecting producers and reaching agreement among them.
A smaller producer set can coordinate efficiently. Voters can replace producers according to the network's rules.
The concern is that participation in production depends on winning and retaining a position. Large voting interests, exchanges holding customer assets, or coalitions can become influential in choosing that set. A system may be open to voters while giving relatively few participants the responsibility for ordering transactions.
For Safex, I want an independent participant to have a direct route into mining without first securing an elected seat.
Proof of authority: identifying approved operators
Proof of authority relies on an approved set of signers. Their identity, reputation, institutional position, or contractual obligations help underpin trust in their operation. The Ethereum documentation on proof of authority explains this model.
It can be suitable when a known group of organizations wants a shared database with clear responsibility.
The tradeoff is the admission process. Someone decides which authorities count. For an open marketplace intended to outlast particular companies or administrators, that is a major limitation.
Byzantine fault tolerant voting: agreeing despite faulty members
Byzantine fault tolerance describes how a system can keep functioning when some participants behave arbitrarily or maliciously.
Classical Practical Byzantine Fault Tolerance uses a known replica set. With at least three times as many replicas as tolerated faulty participants, plus one, it can preserve agreement under its assumptions; progress also depends on the required network conditions. The original PBFT research sets out those assumptions.
This family of protocols is often combined with another mechanism that chooses the participants. A proof of stake network can use Byzantine voting for finality. An institutional network can use it among approved members.
Calling something “BFT” therefore leaves an essential question unanswered: who gets into the voting set, and how is control distributed?
Proof of space and related models
Other systems attach participation to resources such as storage. Chia combines proofs of allocated storage with proofs of time. Its consensus documentation describes the roles of farmers and timelords.
These designs change the resource used to support consensus. They still have to address hardware access, concentration, incentives, and competing histories.
Consensus labels are useful starting points. The actual security model comes from the complete rules and the people operating them.
Why open participation matters to Safex
Safex is intended to make commerce available to people who can contribute something useful. That includes someone who arrives years after the project's beginning.
In my 2016 interview about SafeX, I discussed the importance of people being able to operate network infrastructure from home. I also argued that people should control what they disclose when they transact. The architecture discussed then was an earlier design, but those priorities remain relevant.
Mining creates a route into the economy through operating equipment and contributing work. A miner does not need to acquire SFT, obtain a marketplace account, or persuade existing token holders to elect them before competing to produce Safex blocks.
The distinction is that the resource needed to compete is available outside Safex's existing ownership structure. Someone can enter with equipment and operating resources, and the protocol evaluates their submitted work.
That matters when building an economy intended to remain open to new participants. Early involvement should not be the only meaningful opportunity to take part.
A small participant also needs usable tools. The release of the Safex CPU miner in 2018 was an effort to make participation easier. Software people can understand and run is part of decentralization in practice.
Why Safex uses RandomSFX
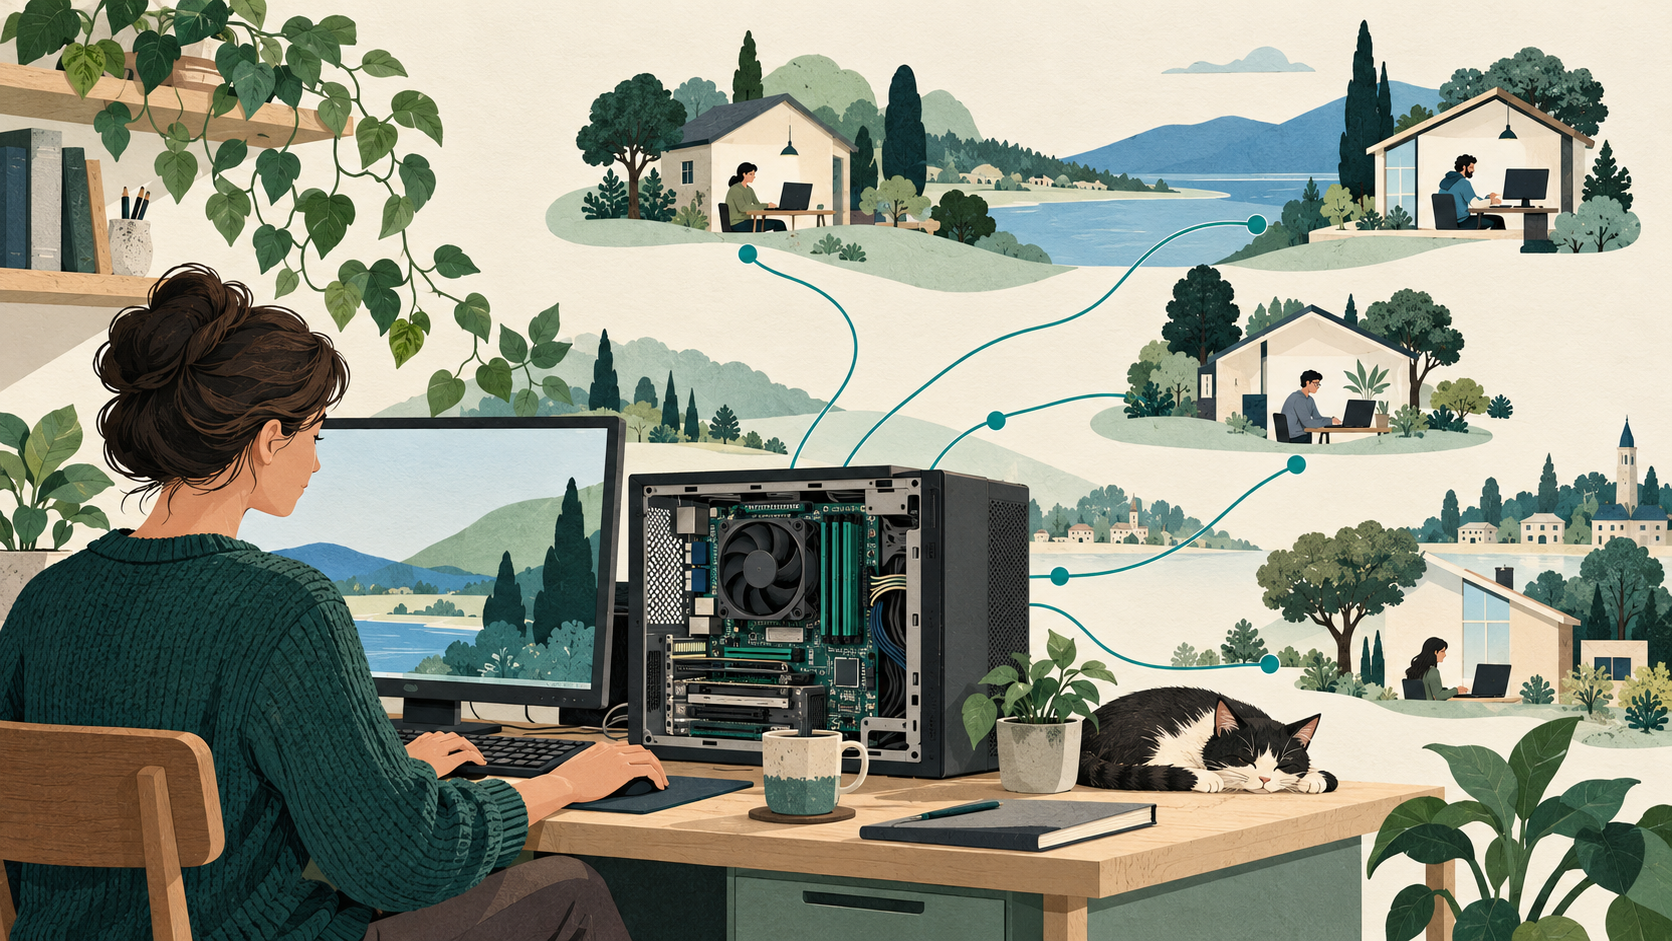
Safex's mining implementation uses RandomSFX, derived from RandomX. The algorithm is designed around general purpose CPUs, random program execution, and memory requirements that reduce the efficiency advantage of specialized hardware. The RandomSFX repository documents that design.
The aim is to make widely available computing equipment useful for participating in network security.
A mining algorithm influences who can realistically compete. If competitive participation depends on a narrow supply of specialized machines, access to manufacturers and large purchasing arrangements becomes important. Supporting ordinary CPUs gives the network a different starting point.
Safex's block validation code checks proof of work and compares cumulative difficulty when considering alternative chains. Its checkpoint rules also form part of that validation.
Keeping participation practical means building usable mining software, supporting independent nodes, and continuing to improve the protocol.
Distribution is part of the design
The question of how money enters circulation has been part of my argument for Safex for years. In the 2018 interview, I connected monetary distribution directly to the objective of building an economy for commerce.
If a currency is intended for broad adoption over time, its distribution deserves more thought than rewarding the earliest discovery of a mining program.
The Safex Blue Paper connected the Cash emission curve to a model of how innovations spread. Adoption begins with a small group, expands, and eventually slows. The intended distribution therefore includes an extended period of meaningful issuance, with rewards rising before declining. The revised Blue Paper explains that rationale.
Safex puts this distribution model into code. Its reward calculation uses predefined emission windows selected from the amount already generated.
Mining and monetary policy are separate design choices that work together. Proof of work determines how miners compete to extend the chain. The emission schedule determines the authorized new currency available through that process.
For Safex, the objective is to keep a path open for people to earn currency and put it to use as the economy develops. People bring the products, services, and customer relationships that give that economy value.
SFX and SFT have distinct responsibilities
Safex Cash and Safex Token are native assets with different jobs. Reducing SFT to a passive fee earning token misses an essential part of the marketplace.
| Function | What Safex uses |
|---|---|
| Payments, purchases, and transaction fees | Safex Cash, SFX |
| New Cash issuance and block production | Proof of work mining |
| Establishing a marketplace seller account | A required commitment of Safex Token, SFT |
| Participation in marketplace fee distributions | A separate SFT staking operation |
| Enforcing the validity of these operations | Nodes applying the protocol rules |
A person can create a wallet and receive coins without first creating a marketplace seller account. These are different things.
The wallet manages keys and assets. The marketplace account establishes a named presence with an account public key and associated data, through which a seller can manage offers.
SFT creates marketplace accounts
To create a marketplace account, you commit SFT in the account creation transaction. Describing that commitment as staking tokens to create the account captures its economic purpose. The implementation treats it separately from the stake used to receive marketplace fees.
The mainnet constants examined for this article require 1,000 SFT, locked for 22,000 blocks. At the target of two minutes per block, that is approximately 30.6 days. The lock is measured in blocks, so the elapsed time can vary. These values are defined in the network configuration.
The committed tokens become spendable after the required lock period, while the marketplace account remains a separate record. Participating in fee distributions uses its own staking operation.
The account command implementation checks matters such as whether the username already exists and whether the account public key is valid. Token requirements and spending restrictions are enforced by blockchain validation.
Committing SFT gives marketplace account creation an economic foundation. The required lock makes mass account creation more costly and ties entry into the marketplace to a commitment of tokens.
In a 2019 forum discussion, I explicitly identified account creation as a primary function of SFT while discussing the separate requirements for revenue staking. I also raised the need for an economic barrier against disposable participation.
That distinction belongs at the center of any explanation of Safex.
SFT fee staking connects marketplace use to its participants
SFT can also be committed through the separate staking mechanism to participate in marketplace fee distributions. This connects a financial incentive to use of the marketplace: purchases generate a fee, and eligible SFT holders receive distributions in Safex Cash.
The mainnet minimum is 25,000 SFT, with a minimum staking period of 8,000 blocks, approximately 11.1 days at the target block interval. Eligibility and distributions also depend on the protocol's staking intervals.
The marketplace fee is 5% of the purchase amount in SFX. It is distinct from the transaction fee paid to miners. The staking system calculates each participant’s SFX distribution based on their eligible staked SFT relative to the total eligible SFT staked during each interval. Accrued Cash is collected through the unstaking process. The database implementation contains that accounting.
The fee serves two connected purposes. It puts a cost on claimed marketplace consumption, making artificial sales volume more expensive to manufacture, and it directs proceeds from that consumption to eligible SFT stakeholders. A distribution requires accumulated fees or another permitted contribution to the pool.
Why marketplace consumption must have a cost
A marketplace needs a way to distinguish meaningful economic use from activity that is cheap to manufacture. Someone controlling both sides of a purchase can move money between their own accounts and report impressive sales volume without attracting an independent customer or delivering a product.
Network transaction fees already impose a cost. A percentage marketplace fee adds a cost that grows with the value of the purchase. Each repeated purchase incurs that charge. This is part of the economic reasoning behind Safex's fee: marketplace consumption carries a commitment, including when the buyer and seller are controlled by the same person.
Distributing the fee to eligible SFT stakeholders gives that cost a destination within the economy. A person manufacturing purchases generally transfers value to other participants through the fee pool. They can recover the portion attributable to their own eligible stake, but the remainder goes elsewhere.
For example, a purchase of 1,000 SFX produces a 50 SFX marketplace fee. If the person controlling both sides is also entitled to 10% of the relevant fee distribution, approximately 5 SFX returns to them and 45 SFX goes to other eligible stakeholders, before considering mining fees and rounding. These illustrative figures assume that the participant’s eligible staked SFT remains 10% of the eligible total during the relevant intervals.
This gives marketplace consumption an economic cost and directs the resulting fees to eligible participants. Those participants include active vendors who can put their distributions back into their businesses.
Vendors can recycle distributions into their businesses
The people receiving marketplace fees can also be the people using the marketplace every day. An active vendor can establish an account, sell products, and separately stake SFT to participate in the fees generated across the network.
That vendor incurs transaction fees when creating or updating listings, moving Cash, and performing other operations. Sales also involve the marketplace purchase fee. SFX received through fee distributions can offset those operating costs and pay for continued use of the system.
For an illustrative accounting period, suppose the eligible fee pool contains 10,000 SFX and a vendor earns 1% of it. That produces approximately 100 SFX in distributions, subject to the actual interval rules and rounding. If the vendor's marketplace charges and network transaction fees for that period total 80 SFX, the distribution can cover those costs and leave 20 SFX for subsequent use.
Vendors pay fees as their operations occur and collect distributions through unstaking. The accumulated fee pool and the amount of SFT they have staked relative to the eligible total determine the amount they receive. They can then apply that Cash to the costs of using the marketplace and continuing their business.
This creates a practical role for SFT in an active business. A vendor can use distributions to recover listing transaction costs, fund future transactions, buy supplies, or purchase services from someone else on Safex. Stakeholders who are customers or developers can likewise spend the Cash they receive in the marketplace.
The same Cash can support successive exchanges as it changes hands. Each useful exchange depends on someone providing something another person wants. Returning fees to participants gives them purchasing capacity that they can put back to work; continued production and demand give that circulation its purpose.
Finance contributes to the productive economy
Finance performs useful work when it helps people make payments, settle obligations, allocate capital, and exchange goods and services. Those services are part of economic production even though their output is not a physical object.
Gross domestic product measures production within an economy over a period. From the industry perspective, the contribution is value added: output less the goods and services purchased as intermediate inputs. The U.S. Bureau of Economic Analysis explains this relationship. Financial services contribute to GDP through the value they add.
That output can be paid for through explicit fees and commissions or through charges embedded in financial arrangements. BEA's description of financial services includes payments, brokerage, financial management, and intermediation, with both explicit and implicit charges. Its explanation of GDP imputations also describes how services supplied by banks can be measured even when no separate fee appears on a customer's statement.
The amount of money moved is different from the value of the service provided. Buying an existing financial asset or recording a capital gain does not, by itself, create new production. BEA makes that distinction in its explanation of financial transactions and the national accounts. A marketplace's gross sales volume likewise cannot simply be called GDP.
This is how I approach the economics of Safex. The network supports payment and settlement, the marketplace supports exchange, and participants bring products and services into that system. Fees connect use of the marketplace to a financial flow that eligible stakeholders can receive and reuse.
Fee distributions allocate the proceeds of marketplace use. Recipients can spend that Cash on goods and services, supporting further economic activity. People produce the value, and finance helps those exchanges take place.
That is why I want marketplace use, SFT participation, and Cash circulation considered together. Vendors can recover costs and continue trading. Customers can spend distributions with those vendors. Developers can earn by improving the tools they use. The objective is an economy whose financial mechanisms support the people doing the work.
These mechanisms assign different responsibilities. The account commitment supports entry into the marketplace. Fee staking connects eligible SFT holders to marketplace activity. Mining provides the work behind block production. Keeping those responsibilities distinct allows commerce to grow without giving account holders or fee recipients control of consensus.
Consensus must serve the commerce people actually do
In 2021, I explained why Safex needed its own blockchain and protocol. My concerns included exposing a customer's financial activity to a seller and making ordinary purchases impractical through transaction costs. I also emphasized interfaces that people could actually use.
Those concerns reach beyond consensus, but they explain the purpose consensus is serving.
Safex includes native operations for marketplace accounts, offers, purchases, and feedback. Its marketplace commands are part of the protocol. The network has to agree on those operations as well as transfers.
Consider a seller registering an account, publishing an offer, receiving a purchase, and building a transaction history. Each step needs valid authorization and an agreed place in the record. A conflicting spend or unauthorized account update must be rejected.
Developers can build on that shared record with tools for product information, delivery coordination, customer communication, and dispute resolution. Each application can serve the needs of its merchants and customers while using the blockchain for authorization and settlement.
Product images, search indexes, and private messages can be handled by applications, with the blockchain maintaining the records that require shared enforcement.
This gives developers room to improve the shopping experience without making every change a change to monetary consensus.
Privacy and mining solve different problems
People need privacy as well as reliable payment records.
A customer buying an ordinary product should not casually reveal their savings, unrelated purchases, or the people who pay them. A business also has legitimate reasons to protect suppliers, margins, and commercial relationships.
These were concerns in my early public discussions of SafeX. They are part of making commerce safe enough for ordinary use.
Proof of work secures the accepted transaction history. Privacy comes from the transaction design and the way wallets handle information. These are complementary parts of the system.
Safex incorporates ring signatures and one time destination keys into its transaction construction. These cryptographic mechanisms support privacy in payments and commerce.
A seller's public marketplace identity is also different from a customer's wallet privacy. Commerce needs ways to recognize a merchant and evaluate a record without turning every payment into a map of a person's life.
How participation strengthens the network
Proof of work turns the resources contributed by miners into protection for the shared transaction record. Continued participation sustains that work as the economy develops.
Mining commits equipment and electricity to the network. That continuing expenditure supplies the work behind block production and makes competing histories costly to produce. For Safex, this supports a marketplace whose records participants can verify and whose operation they can join.
Pools help miners coordinate their work and receive more regular payouts. The Bitcoin mining guide explains how pooled work and rewards are organized. Independent pool operators and miners choosing where to direct their work are part of maintaining distributed participation.
For Safex, supporting independent miners, node operators, and well maintained software is part of building the ecosystem.
Protocol changes take effect through the software that participants choose to adopt. Developers, miners, node operators, businesses, and users all have roles in deciding which network they will continue to support.
Open source code makes inspection and independent development possible. Careful releases, security review, and dependable infrastructure support the people who use and maintain the network.
Expanding Safex means making the system useful and durable
The measure of progress is whether more people can do something worthwhile with the network.
A miner contributes work. A seller brings goods or services. A customer creates demand. A developer makes participation easier. An independent node operator checks the rules. Together, these activities sustain the economy.
That is why expanding the ecosystem matters. More accessible wallets, merchant software, independent infrastructure, clear documentation, and practical ways to acquire and spend Cash increase the number of people who can participate.
Expansion should preserve choice. A protocol becomes more useful when several independent applications can read its records and people can retain control of their keys.
A marketplace account and its history should provide a foundation that new software can continue to use. Compatible applications, reliable access to chain data, and careful treatment of private information make that continuity practical.
My reason for choosing proof of work is connected to that larger objective. I want people who arrive later to have a route into operating the network. I want Cash to circulate through useful work and trade. I want SFT to support marketplace accounts and participation in commerce without turning token ownership into authority over block production.
People should be able to build something online and keep making progress with it.
Safex needs consensus that supports that ambition, privacy that protects the people involved, and an ecosystem capable of putting both to use. Proof of work provides the basis for block production; the work of building the economy continues with everyone who participates.
Sources and protocol notes
Historical interviews and forum posts above document the development of these arguments. They describe the proposals and circumstances of their own dates.
Safex parameters in this article were checked against safexcore commit 031d1031be0d64adadefac0a8e1c85c813423d11, reviewed on October 15, 2026. The account lock and fee staking descriptions follow the implemented rules.